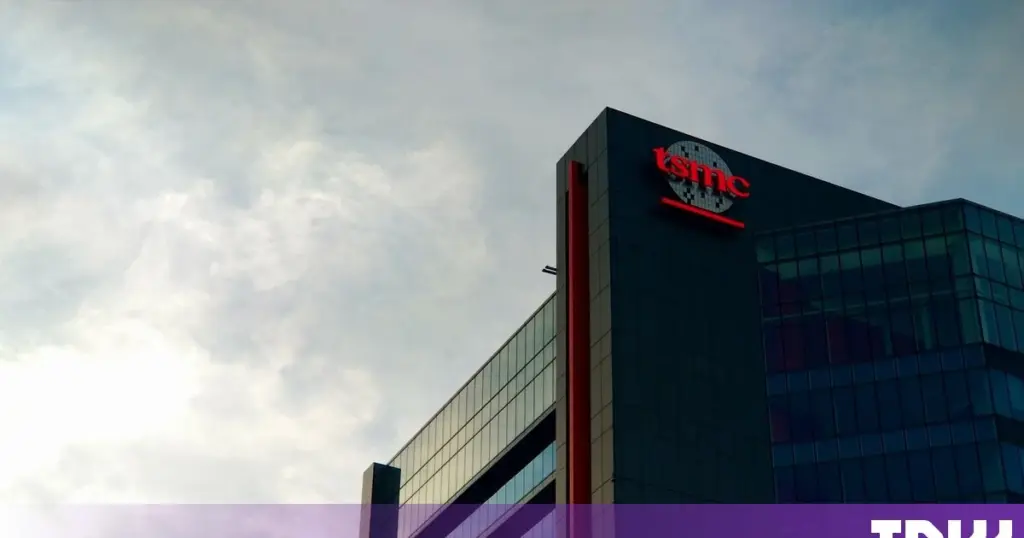
- TSMC has officially denied reports of exploring 3D DRAM memory chip production.
- The rumors emerged amid a global memory shortage driven by surging AI hardware demand.
- The company reiterated its commitment to remaining a pure-play logic foundry.
TSMC Rejects 3D DRAM Manufacturing Reports
TSMC, the world’s largest contract chip manufacturer, has officially denied recent reports suggesting it is exploring the production of 3D DRAM memory chips at the request of its major customer, Nvidia. Earlier, The Information had reported that TSMC had begun drafting plans for 3D DRAM amid a growing memory scarcity driven by the boom in artificial intelligence.
A TSMC spokesperson stated, “Please note that TSMC focuses on our core business at all times, which is dedicated IC foundry. Our mission is to be the trusted technology and capacity provider of the global logic IC industry for years to come.” This statement effectively denies the company’s intention to venture into DRAM manufacturing.
Context of the Rumors and Memory Shortages
The speculation about TSMC entering the 3D DRAM market arose from the severe global shortage of memory chips, particularly crucial for high-performance AI systems. The rapid increase in demand for AI hardware has elevated memory from a commodity to a strategic asset. If TSMC were to pursue 3D DRAM production, it would put the company in direct competition with established memory giants like Samsung, SK Hynix, and Micron, significantly expanding its role in the AI supply chain.
The Information, citing two individuals familiar with the initiative, claimed that TSMC had started preparing plans for 3D DRAM manufacturing, reportedly overseen by Hsu Kuo-chin, TSMC’s vice president for advanced packaging and former head of Micron’s Taiwanese operations. However, TSMC has publicly refuted these claims.
Technological and Market Hurdles
Manufacturing DRAM, especially 3D DRAM, requires fundamentally different production processes and expertise than those possessed by TSMC as a logic chip foundry. 3D DRAM involves stacking multiple layers of memory cells vertically to increase density, a complex endeavor even for leading memory makers. Developing competitive 3D DRAM technology without a foundational planar DRAM process is extremely challenging, and TSMC currently lacks both.
Entering the DRAM market also exposes TSMC to substantial market risks. The memory sector is notoriously cyclical, often experiencing periods of oversupply and price depression following capacity expansions. Furthermore, such a move could complicate TSMC’s relationships with existing DRAM manufacturers, including SK Hynix, with whom TSMC partnered in 2024 to manufacture logic base dies for next-generation HBM products.
Alternative Strategies for TSMC
TSMC can expand its presence in the advanced memory market without directly manufacturing DRAM. This includes producing sophisticated logic base dies for HBM, integrating memory with processors using its SoIC hybrid bonding technology, and developing customized memory solutions with partners such as GUC and established DRAM manufacturers. This approach allows TSMC to capture a larger share of the value generated by DRAM without investing billions of dollars in developing competitive DRAM process technologies from scratch and building additional fabs.
TSMC’s official denial signifies its firm commitment to its pure-play logic foundry strategy. This indicates that despite pressure from key customers like Nvidia and the surging demand for specialized AI memory, TSMC does not currently plan to compete with Samsung, SK Hynix, and Micron in DRAM production. Instead, its focus will likely remain on advanced packaging and integration, enabling it to indirectly participate in the high-performance memory market’s growth while avoiding the inherent risks and complexities of direct DRAM manufacturing.
TSMC’s reaffirmation of its pure-play logic foundry model is entirely consistent with its strategic focus and core competencies. Venturing into 3D DRAM production would necessitate a fundamental shift in process technology, requiring extensive capital expenditure and expertise divergent from its established FinFET and GAAFET logic fabrication. The inherent cyclicality and lower margins of the memory market, coupled with the competitive landscape dominated by Samsung, SK Hynix, and Micron, present significant disincentives for a company optimized for leading-edge logic. Their current collaboration on HBM logic base dies is a more synergistic approach.