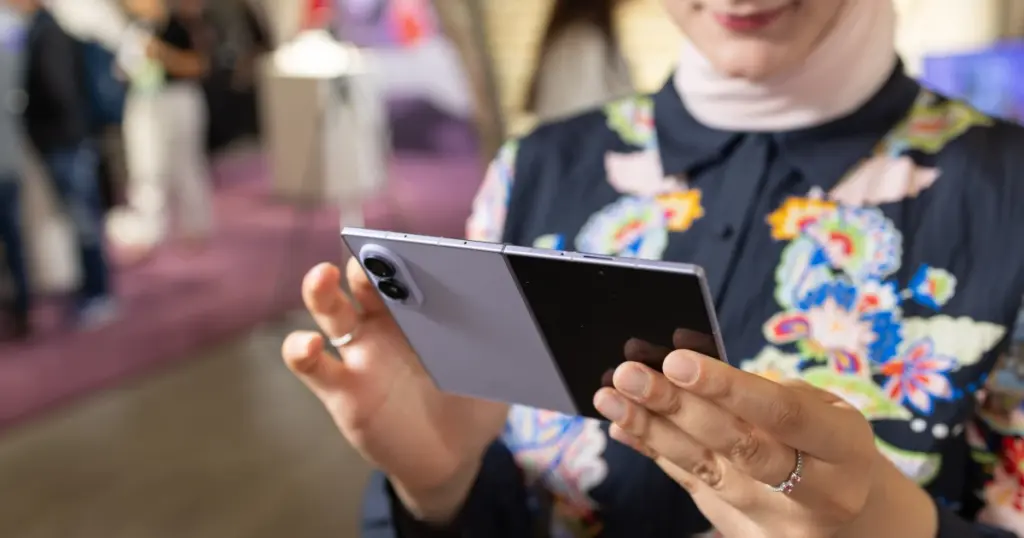
- Global smartphone shipments plummeted by 20% to 22% year-on-year in Q3, marking the lowest market level in over a decade.
- Memory component prices have skyrocketed approximately 350% since last year, fueled by unrelenting enterprise AI demand.
- Apple and Samsung now command 45% of total shipments, leaving low-end and budget-oriented hardware manufacturers heavily squeezed.
Shipments Tumble to Historic Multi-Year Lows
The global smartphone market has recorded its most severe contraction in over a decade as hardware supply chains reel from an unprecedented memory supply crunch. According to preliminary quarterly findings released by market intelligence firms IDC and Omdia, worldwide smartphone shipments plummeted by 20% to 22% year-on-year in the third calendar quarter, sinking to levels not witnessed in 14 years.
Total shipments during the quarter were pegged at approximately 255 million to 255.3 million units. Counterpoint Research highlighted that escalating retail price tags are aggressively straining consumer spending power, accelerating a drop in replacement cycles.
The AI Memory Crunch: Component Inflation at 350%
Widely designated across industry circles as “RAMageddon,” the crisis is driven by intense competition for fabrication capacity, with semiconductor manufacturers prioritizing high-margin AI accelerator memory over consumer electronics. IDC reports that baseline memory component costs have surged by roughly 350% since last year and continue to trend upward.
While sequential memory inflation tempered slightly in Q3 to low double-digit increases-down from earlier quarterly spikes of 50% to 100%-broader bill-of-materials costs remain elevated. To preserve gross margins, device manufacturers are scaling back budget portfolios and resorting to cost-reduction trade-offs, such as downgrading display glass, camera image sensors, and RF modules.
| Key Market Metrics | IDC Estimates | Omdia Estimates |
|---|---|---|
| Q3 Shipment Decline (YoY) | -22% | -20% |
| Total Channel Shipments (Q3) | 255.3 million units | ~255 million units |
| Memory Cost Increase Since Last Year | +350% | Persistent demand-supply gap |
| Projected 2026 Market Contraction | Prolonged downturn | -12% (followed by -6% next year) |
| Projected Industry Recovery Timeline | Not before 2028 | Not before 2028 |
Market Polarization: Premium Brands Solidify Grip
Surging production expenses have triggered substantial consolidation across market tiers. Omdia reveals that the premium duopoly of Samsung and Apple expanded its joint footprint to roughly 45% of total worldwide shipments, representing an 8 percentage-point increase compared to the previous year. Price-sensitive segments, by contrast, are bearing the brunt of the downturn.
Hardware retailing above the $400 threshold has demonstrated structural resilience, emerging as the sole area positioned for potential growth. Analysts caution that standard fourth-quarter seasonal lift, promotional campaigns, and new flagship launches will not be sufficient to offset systemic cost pressures.
Extended Horizon: Relief Unlikely Before 2028
Research analysts project an extended period of contraction rather than a quick rebound. Omdia forecasts an overall 12% decline in smartphone shipments across 2026, followed by a further 6% drop the subsequent year. IDC Senior Research Director Nabila Popal warned that the sector has yet to establish a cyclical bottom.
Speaking to The Register, Omdia Principal Analyst Runar Bjorhovde stated that relief is improbable prior to 2028 at the earliest due to deep-seated structural imbalances between silicon production and aggregate demand. Industry stabilization will hinge on price plateauing, an inflection point suppliers have yet to achieve.
Consumers should prepare for higher baseline prices across mid-range and entry-level phones, or expect noticeable hardware downgrades in secondary specifications like cameras and screens. Deep discounts will remain scarce through the coming product cycles as vendors prioritize premium devices with sustainable profit margins.
We’ve definitely felt this squeeze managing our company’s field devices; newer mid-range phones are cutting corners on displays and cameras just to keep 6GB RAM. Performance stays smooth, but durability suffers. If you’re buying fleet or personal phones now, look for certified refurbished flagships from two years ago—you get far better build quality and sustained RAM for the same price.